Mortgage rates above 7% through 2027: what buyers can do

The Mortgage Bankers Association expects 30-year mortgage rates to stay above 7% through the end of 2027. If you already know you’ll buy in the next year, waiting for rates to drop isn’t much of a plan, and the slower months before spring are when buyers usually have the most room to negotiate.

What the MBA just said

At its annual convention this month, the MBA released its updated forecast. It has the 30-year rate averaging about 7.3% for the rest of 2026 and staying above 7% all through 2027. MBA’s economists also expect the Fed to raise rates again in December and once more early next year. (MBA, Realtor.com)

For context, Freddie Mac’s weekly average hit 7.40% on Oct 8, the highest in about three years. A year earlier it was 6.30%. (Freddie Mac)

MBA also pointed out that purchase activity dropped off once rates got into the 7% range, and that more buyers are turning to adjustable-rate loans or paying points to get a lower rate. (BAM)

My take: the rate isn’t coming to save anybody

If you’ve been waiting for rates to come back down before you start looking, I get it. Nobody’s excited about a 7 in front of their rate. I’m not going to pretend it’s comfortable.

But the people whose whole job is forecasting this are telling us it isn’t coming down in any meaningful way next year. Forecasts miss sometimes. Still, “maybe they’re wrong” is a rough thing to build a move around.

So the question changes. It’s not “when do rates drop?” It’s “if this is the rate, how do I get the best deal I can?”

And right now, that question has a better answer than it’s had in a while.

What’s happening in the South Metro

Buyers have stepped back, and homes have piled up.

Nationally, mortgage applications to buy a home were down 15% from a year earlier in early October. (Calculated Risk) You can see the same thing here.

In September, there were 1,166 previously owned homes for sale across the South Metro area I track, up 30.9% from 891 a year earlier. Pending sales went the other direction, down 5.9% (from 376 to 354).

That pushed months of supply to 3.1, up from 2.4 last September. Months of supply is how long it would take to sell every home on the market if nothing new got listed. The higher it goes, the more choice buyers have. And 3.1 is the highest it’s been in my data going back to January 2023.

To be straight with you, 3.1 months still isn’t what most people would call a buyer’s market. That usually takes something closer to six. But it’s the most choice South Metro buyers have had in years, and it’s tilting their way.

I’m seeing more buyers successfully negotiate on price and concessions right now, and the agents in my office are seeing the same thing. A year or two ago, a lot of those asks would’ve been a nonstarter.

Source: Northstar MLS, previously owned homes, my South Metro area, September 2025 vs. September 2026. Data deemed reliable but not guaranteed.

Why the next few months may matter more than spring

Here’s what usually happens around here.

Come February, the buyers who sat out waiting for rates to fall start to realize they’re not falling. New listings show up. Spring does its thing, and everybody comes back at once.

The numbers show it pretty clearly. Pending sales in my area went from 223 in December 2025 to 277 in February and 429 in March. That’s up 92% from December to March. The year before followed the same shape: 218, then 307, then 409. New listings roughly tripled from December to March both years.

If the MBA’s forecast holds, spring buyers will be shopping at the same 7%-plus rate you’d get today. The difference is you’d be competing with all of them.

None of this means you have to buy this fall. If you’re not sure you’ll want to move in the next year, don’t let a forecast rush you into it. But if you already know you will, this stretch deserves a serious look.

Ways buyers are working around a 7% rate

There are more options here than most people realize. A few I’m seeing and talking through with buyers:

  • Asking the seller to cover closing costs. With more homes sitting, more sellers are open to it.
  • Using seller-paid costs to buy down your rate. Instead of putting a concession toward closing costs, some buyers put it toward points to lower the rate. Loan programs set limits on how much a seller can contribute, so check with your lender first.
  • Adjustable-rate mortgages. ARMs were about 10% of applications over the past month, and they’ve been running roughly 0.8 percentage points below fixed rates. (HousingWire) The catch: after the fixed period ends, your rate and payment can go up. Know the worst-case number before you sign.
  • Interest-only loans. A few buyers have asked me about these. Payments are lower early on because you’re not paying down the loan yet. That’s also the downside. When the interest-only period ends, the payment jumps. They’re not for most people.

Every one of these has a tradeoff. The right one depends on how long you plan to stay and what your budget can handle if things change. Talk with your lender before you pick one. If you don’t have one yet, I’m happy to connect you with someone I trust.

More on financing in my rates and financing posts and on the buying process in my posts for buyers.

What to watch

  • Freddie Mac’s weekly rate, out every Thursday.
  • MBA’s weekly mortgage applications, out every Wednesday. It’s the quickest read on whether buyers are coming back.
  • The Fed’s December meeting, where MBA expects another quarter-point hike.
  • February listings and pendings in the South Metro. That’s when we’ll see whether the spring rush shows up on schedule. I’ll post the numbers.

If rates really do stay above 7% through next year, does that change when you’d buy, or are you still waiting it out? I’d like to hear it.

FAQ

Will mortgage rates go down in 2027?

The Mortgage Bankers Association doesn’t expect much relief. Its October 2026 forecast has 30-year rates staying above 7% through the end of 2027. Forecasts can miss, but that’s the current outlook from one of the main industry groups that tracks it.

Is it a buyer’s market in the South Metro right now?

Not by the traditional definition, which usually means about six months of supply. In September 2026 the South Metro area I track had 3.1 months of supply, up from 2.4 a year earlier and the highest since at least January 2023. It’s tilting toward buyers, and more buyers are negotiating on price and concessions.

Is it better to buy in the fall or the spring?

It depends on your situation, but fall and winter usually bring less competition. In the South Metro, pending sales nearly doubled from December 2025 to March 2026, so spring buyers tend to compete with a lot more people.

Can a seller pay to buy down my interest rate?

Often, yes. Seller concessions can usually go toward points that lower your rate, within the limits your loan program sets. Your lender can tell you exactly what’s allowed for your loan.

Are adjustable-rate mortgages a good idea right now?

They can be for some buyers, especially those who don’t plan to stay long. ARMs start lower than fixed rates, but the rate can rise after the fixed period. Make sure you know the highest your payment could go before choosing one.

Sources

  • Mortgage Bankers Association, “MBA Forecast: Mortgage Originations to Decrease 5 Percent in 2027 as Mortgage Rates Remain Above 7 Percent,” Oct 11, 2026. mba.org
  • Realtor.com (Keith Griffith), “Mortgage Rates Will Remain Above 7% Through 2027, Top Economist Forecasts,” Oct 11, 2026. Yahoo Finance
  • BAM (Sarah Lentz), “Mortgage Rates Above 7% Through 2027, According to MBA’s Latest Forecast,” Oct 13, 2026. nowbam.com
  • Freddie Mac, “Mortgage Rates Average 7.40%,” Oct 8, 2026. freddiemac.com
  • Calculated Risk, “High Frequency Data: Recent Surge in Mortgage Rates Impacting Existing Home Supply and Demand,” Oct 7, 2026. calculatedrisk.substack.com
  • HousingWire, “Mortgage applications fall 6% as rates hit highest level in three years,” Sept 30, 2026. housingwire.com
  • Northstar MLS via InfoSparks, previously owned homes, My South Metro Area, January 2023 to September 2026, pulled Oct 14, 2026.

Published Oct 14, 2026 by Travis Wyman.
The $27,000 Pricing Gap: What Buyers and Sellers Need to Know

If you’re planning to buy or sell a home in 2025, there’s a key trend you need to know: buyers and sellers aren’t seeing eye to eye on price. A recent Clever Real Estate survey revealed a $27,000 gap between what buyers expect to pay and what sellers hope to get. Buyers are budgeting around $386,507, while sellers are aiming for $413,976.

So, what’s driving this pricing gap, and how can you navigate it? Let’s break it down.

What’s Behind the $27,000 Pricing Gap?

Sellers Are Riding High on Confidence

After years of rising home prices, sellers are entering 2025 with optimism. In fact, 74% of sellers believe they’ll sell at or above asking price. However, with market conditions stabilizing, these high expectations may not always align with buyer budgets.

Buyers Are Feeling the Pinch

On the flip side, buyers are grappling with rising mortgage rates and affordability challenges. Nearly 68% worry escalating prices will delay their purchase plans. Budget constraints often lead to tougher negotiations or missed opportunities.

While 87% of buyers and sellers expect strong demand in 2025, housing economists predict smaller price increases compared to previous years. This stabilization could mean buyers have more negotiating power, while sellers might need to rethink pricing strategies.

Tips for Buyers: How to Bridge the Gap

Navigating the $27,000 gap can feel overwhelming, but these strategies can help:

  • Know Your Market: Research local home prices and trends. Being informed gives you an edge in negotiations.
  • Be Flexible: If you can’t meet the asking price, consider other ways to sweeten your offer, like flexible closing dates or waived contingencies.
  • Leverage Stabilizing Prices: Slower price growth in 2025 could work in your favor during negotiations.

Tips for Sellers: Attracting the Right Offers

Sellers, getting top dollar means setting realistic expectations and preparing your home to shine. Here’s how:

  • Price Strategically: Partner with a local real estate expert to price your home competitively. Nearly 49% of agents agree pricing is the key to a quick sale.
  • Stage Your Home: Professional staging or high-quality photos can help justify your asking price.
  • Stay Open to Negotiations: Flexibility can mean the difference between a quick sale and a prolonged listing.

What the Pricing Gap Means for the 2025 Real Estate Market

The $27,000 pricing gap highlights a broader trend in the housing market: cautious buyers versus confident sellers. Bridging this gap will require both sides to adjust their expectations. For buyers, it’s about realistic budgeting and smart negotiations. For sellers, it’s understanding market trends and pricing your property to attract serious offers.

With the right strategies and a little compromise, 2025 could be a great year for both buyers and sellers.

TL;DR

  • Buyers expect to spend $386,507, while sellers aim for $413,976—a $27,000 pricing gap.
  • Sellers are confident, but buyers are cautious due to rising costs and mortgage rates.
  • Strategic planning and realistic expectations are key for navigating the 2025 real estate market.

Are you ready to tackle the 2025 housing market? Let’s work together to achieve your goals!

How Homeownership Is Life Changing for Many Women

Throughout Women’s History Month, we reflect on the impact women have in our lives, and that includes impact on the housing market. In fact, since at least 1981, single women have bought more homes than single men each year, and they make up 17% of all households.

Why Is Homeownership So Important to Women?

The rise in women pursuing homeownership hasn’t just made an impact on the housing market. It’s also been an asset for those buyers and their households. That’s because homeownership has many benefits, both financial and personal.

On the financial side, housing proves to be the key to building wealth for single women. Ksenia Potapov, Economist at First American, says:

“For single women, housing has always made up a large share of total assets. Over the last 30 years, the average single woman’s wealth has increased 88% on an inflation-adjusted basis, from just over $142,000 in 1989 to $267,000 in 2019, and housing has remained the single largest component of their wealth.”

The financial security and independence homeownership provides can be life changing, too. And when you factor in the personal motivations behind buying a home, that impact becomes even clearer.

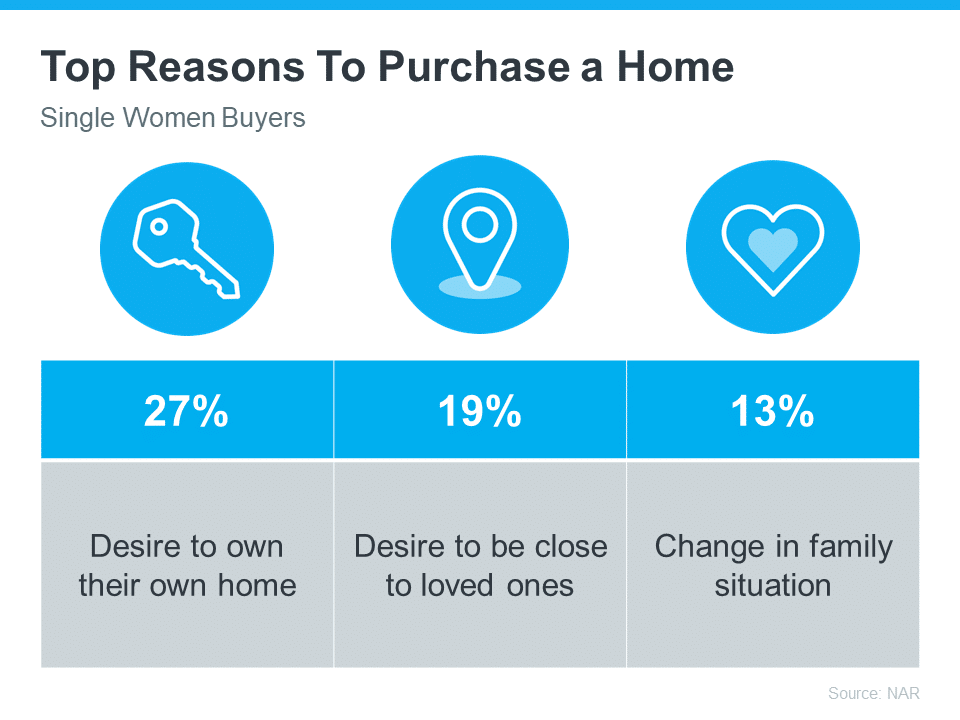
A recent report from the National Association of Realtors (NAR) shares the top reasons single women are buying a home right now (see chart below):

Bottom Line

Homeownership can be life changing no matter who you are. Let’s connect today to talk about your goals in the housing market.

Why Buying a Home Is a Sound Decision

If you’re thinking about buying a home, you want to know the decision will be a good one. And for many, that means thinking about what home prices are projected to do in the coming years and how that could impact your investment. 

This year, we aren’t seeing home prices fall dramatically. As the year goes on, however, some markets may go up in value while others may lose value. That’s why it’s helpful to keep the long-term view in mind. Experts project a return to a steadier rate of price appreciation in the years that follow.

Home Price Appreciation in the Years Ahead

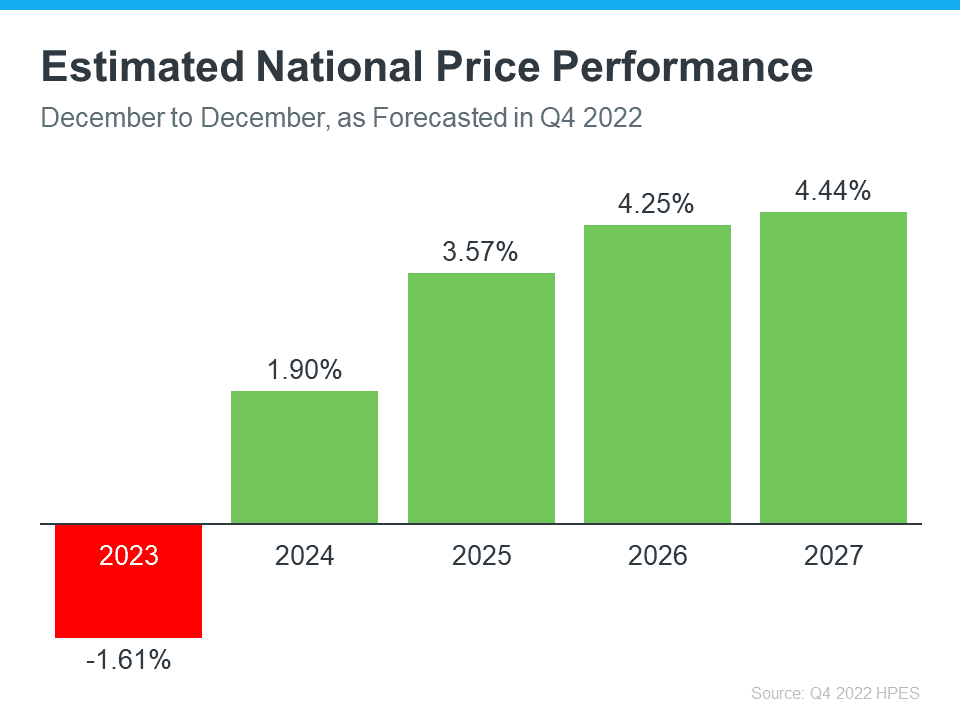
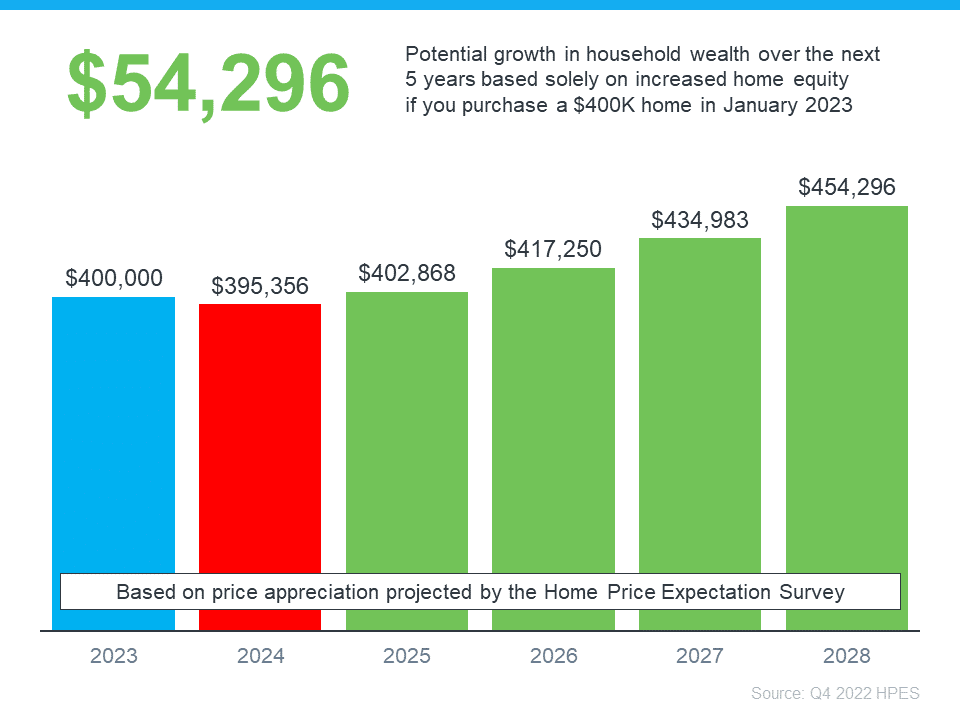
Over 100 economists, investment strategists, and housing market analysts were polled by Pulsenomics in their latest quarterly Home Price Expectation Survey (HPES). The report indicates what they believe will happen with home prices over the next five years. As the graph below shows, after mild depreciation this year, these experts forecast home prices will return to more normal levels of appreciation through 2027.

The big takeaway is experts aren’t forecasting a drastic fall in home prices nationally, even though some markets will see home price appreciation while others may depreciate. And when they look further out, they see steady price appreciation in the long run. That’s a great example of why homeownership wins over time.

What Does This Mean for You?

Once you buy a home, price appreciation raises your home’s value, and that grows your household wealth. Here’s how a typical home’s value could change over the next few years using the expert price appreciation projections from the survey mentioned above (see graph below):

In this example, if you bought a $400,000 home at the beginning of this year and factor in the forecast from the HPES, you could accumulate over $54,000 in household wealth over the next five years. So, if you’re wondering if buying a home is a sound decision, keep in mind what a strong wealth-building tool it is long term.

Bottom Line

According to the experts, while we may see slight depreciation this year, home prices are expected to grow over the next five years. If you’re ready to become a homeowner, know that buying today can set you up for long-term success as home values (and your own net worth) are projected to grow. Let’s connect to begin the homebuying process today.

Reasons To Consider Condos in Your Home Search

Are you having trouble finding a home that fits your needs and your budget? If so, you should know there’s an option worth considering – condominiums, also known as condos. According to Bankrate:

“A condo can be a more affordable entry point to homeownership than a single-family home. And as a homeowner, you’ll build equity over time and have access to tax benefits that a renter wouldn’t.”

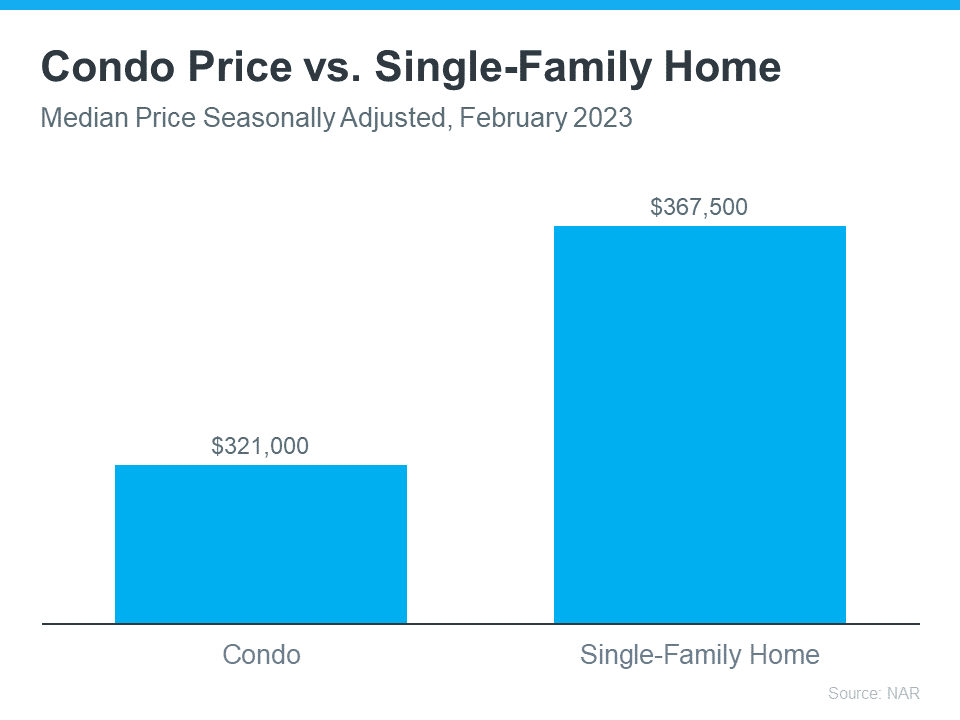
That’s why expanding your search to include additional housing types, like condominiums, could help you accomplishyour homeownership goals this spring, especially if you can be flexible about the space you need. Condos are typically smaller than a single-family home, but that’s part of what can make them more budget-friendly (see graph below):

In addition to providing more options in your home search and possibly your price point, there are several other benefits to condo living. They tend to require less upkeep and lower maintenance – and that can give you more time to spend doing the things you enjoy. Plus, since many condos are in or near city centers, they offer the added benefit of being in close proximity to work and leisure.

Remember, your first home doesn’t have to be your forever home. The important thing is to get your foot in the door as a homeowner so you can start building wealth in the form of home equity. In time, the equity you develop can fuel a future purchase if your needs change.

Ultimately, owning and living in a condo can be a lifestyle choice. And if that appeals to you, they could provide the added options you need in today’s market.

Bottom Line

It could make a lot of sense to add condos to your home search. Let’s connect today if you’re ready to check out the options in our area.